Kuwait’s PIC Reported Among Suitors for Shell US Chemicals Assets Valued at Up to 8 Billion Dollars
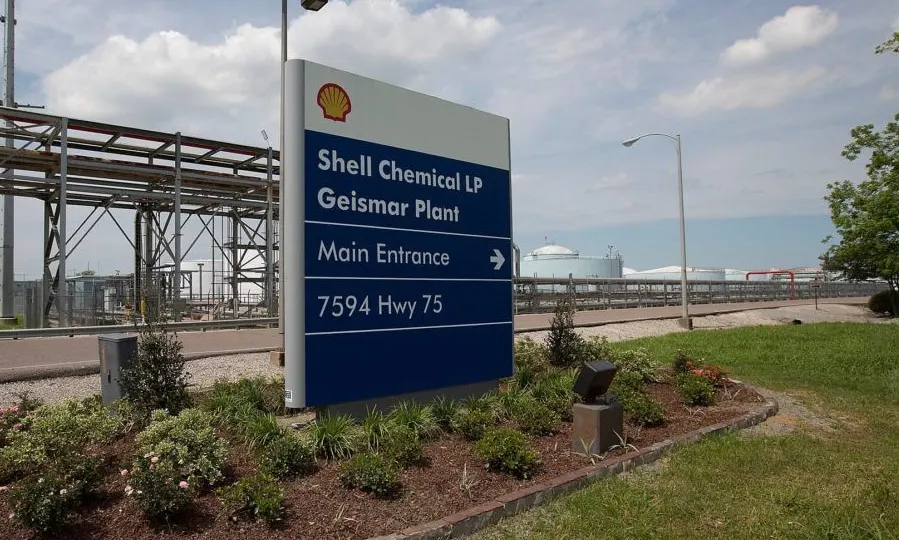
Kuwait’s Petrochemical Industries Company, the petrochemical arm of Kuwait Petroleum Corporation, has been reported among the parties interested in Shell’s US chemicals assets, in a sale process that the Financial Times says could value the portfolio at as much as 8 billion dollars.
The Financial Times reported, in an account carried by Reuters, that potential buyers submitted non-binding offers in July for individual assets or the entire US chemicals business, and that the interested parties include ExxonMobil, LyondellBasell, Apollo Global Management and the chemicals arm of state-owned Kuwait Petroleum Corporation. Shell, the three named companies and Kuwait Petroleum had not commented. No preferred buyer has been named and there is no binding transaction. PIC’s interest is a reported one at this stage, not a confirmed bid.
| Reported transaction indicators | Scale |
|---|---|
| Potential portfolio valuation | Up to 8bn dollars |
| US chemicals sites | 4 (Pennsylvania, Louisiana, Texas) |
| Monaca polymer capacity | 1.6mn tonnes/year |
| Offer stage | Non-binding, submitted July |
| PIC 2040 base-petrochemicals target | 14.5mn tonnes/year |
| PIC 2040 derivatives target | 1.2mn tonnes/year |
Shell’s US chemicals operations span four sites in Pennsylvania, Louisiana and Texas. Among the largest is Shell Polymers Monaca in Pennsylvania, which began operations in 2022 with designed capacity of about 1.6 million tonnes of polymers a year.
The opportunity aligns with PIC’s stated strategy. PIC targets 14.5 million tonnes a year of base petrochemicals by 2040, together with a 1.2 million tonne derivatives ambition, and identifies new projects, expansions and acquisitions with partners as its routes to that goal. Monaca’s 1.6 million tonnes of annual capacity is equivalent to about 11 percent of PIC’s 2040 base-petrochemicals target, our calculation, so an asset of this size would be strategically relevant even before the precise package PIC might seek is known.
Shell’s own disclosures frame the reported valuation. At its 2025 Capital Markets Day, Shell presented about 14 billion dollars of 2024 capital employed at Shell Monaca and around 5 billion dollars in its US Gulf Coast chemicals operations, roughly 19 billion dollars across the two US groupings, and said it intended to pursue strategic or partnership options in US chemicals and reduce capital employed by 2030. At the upper end of the reported range, 8 billion dollars equals about 42 percent of that 19 billion dollar reference, our calculation, though capital employed and transaction value are different measures and the exact perimeter of any sale may not match Shell’s presentation categories.
| Shell US chemicals reference | Amount |
|---|---|
| Monaca 2024 capital employed | ~14bn dollars |
| US Gulf Coast capital employed | ~5bn dollars |
| Combined reference | ~19bn dollars |
| Reported potential sale value | Up to 8bn dollars |
The possible sale fits a strategic shift Shell set out before this process. Chief Executive Wael Sawan said Shell intended to reduce capital employed in chemicals while remaining open to partnerships. The financial record helps explain the approach: Shell’s chemicals division was loss-making in 2025 and again in the first quarter of 2026, before returning to positive adjusted earnings of 354 million dollars in the second quarter of 2026. The reported process is therefore better read as portfolio reallocation than a distressed disposal.
For PIC, a transaction of this scale would extend an international push already visible in its portfolio. In April 2025 PIC agreed to invest 638 million dollars for a 25 percent stake in Wanhua Petrochemical in Yantai, China. An 8 billion dollar transaction would be about 12.5 times that investment, our calculation, although PIC has not been confirmed as seeking the whole Shell portfolio and any deal could involve individual assets or partners.
Why it matters: Established US assets would give a buyer immediate capacity, customers, logistics and market access without the construction and ramp-up of a new build, and Monaca sits close to US polyethylene demand with access to shale-derived ethane feedstock. The eventual economics would depend not on added capacity alone but on the purchase price, utilisation, petrochemical margins, feedstock costs and integration into an existing portfolio, which is why a reported interest at the non-binding stage should not be read as an agreed acquisition.
Outlook: The markers are whether the process moves past non-binding offers to a named buyer, which assets any bidder pursues, and the price and structure of any deal. Confirmation from PIC, KPC or Shell, none of which has commented, would be the point at which a reported interest becomes a transaction.
Sources: Financial Times, carried by Reuters, 24 August 2026; Petrochemical Industries Company; Shell; Wanhua Chemical.