
Saudi Arabia Sets a 2 Percent Fee on Non-Saudi Property Disposals as It Opens Real Estate Wider
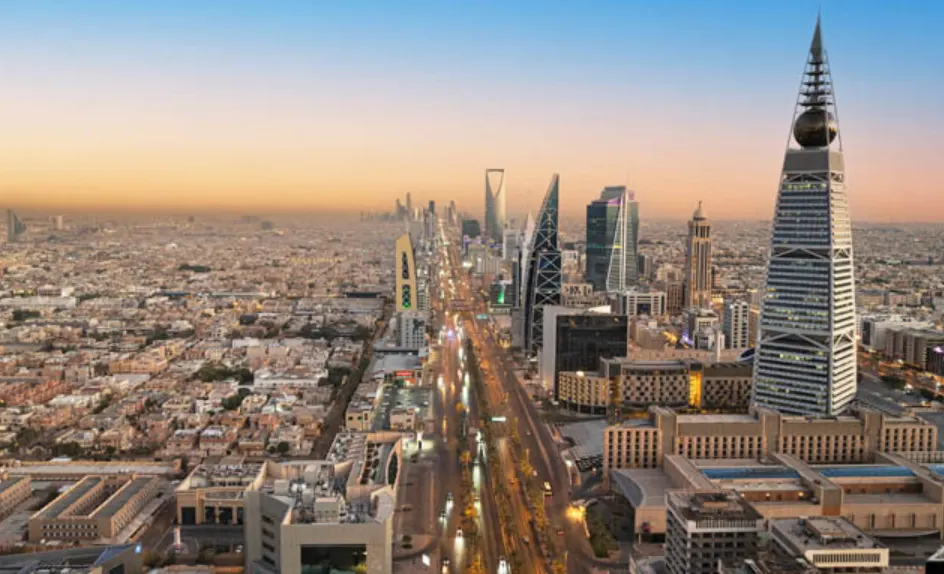
Saudi Arabia is opening property ownership to non-Saudis under executive regulations approved by the Council of Ministers on 23 June, with reporting on the rules indicating a 2 percent fee on a foreigner’s disposal of real-estate rights. The regulations give investors the operating detail for a market the authorities want to widen to international buyers.
The enabling law authorises the Real Estate General Authority to levy a fee of up to 5 percent on a non-Saudi’s disposal of real-property rights, and the executive regulations are reported to set the applied rate at 2 percent, collected by the authority and applying across residential and commercial use in the cities and governorates of Riyadh, Mecca, Medina and Jeddah. Setting the applied rate at 2 percent, about 40 percent of the statutory ceiling, our calculation, signals that the authorities want to raise revenue and formalise transactions without deterring the foreign demand the reform is designed to attract. Exemptions apply to inheritance, transfers under a final court judgment, and expropriation for public benefit. It is worth noting that the legal language covers disposals of real-estate rights broadly, not only outright sales.
The fee sits within a wider framework that has moved in clear steps. The Law of Real Estate Ownership by Non-Saudis was approved in July 2025, published in the official gazette later that month, and entered into force 180 days later, on 22 January 2026, replacing a two-decade-old ownership regime. The executive regulations approved on 23 June 2026 are the operational layer that makes the law usable, so from the law’s publication to the detailed rules the process ran about eleven months, our reading of the timeline, a deliberate sequencing that gave the market time to prepare.
Ownership is organised on a designated-zone model rather than a blanket opening. Approved areas in Riyadh include the King Abdullah Financial District, Diriyah Gate, New Murabba and Qiddiya, while Jeddah, AlUla and the giga-projects such as NEOM and the Red Sea developments have their own designated zones, each specifying permitted ownership rights. The law also allows a non-Saudi to own a single property outside the designated zones for residential use. Mecca and Medina carry tighter controls in keeping with their status: non-Saudi individuals may own there only if they are Muslim, foreign companies are generally restricted, and ownership is confined to pre-approved developments.
The commercial backdrop is a large and growing market. Third-party estimates put the Saudi real-estate market at about 77 billion dollars in 2025, projected to reach roughly 141.6 billion dollars by 2034, an annual growth rate of about 6.7 percent, figures that are market-size forecasts rather than official government targets and should be read as such. What the reform changes is who can participate in that growth, opening a market that was largely closed to foreign individuals and companies to a broader base of international capital.
The measure also places Saudi Arabia within a competitive regional context. The United Arab Emirates has allowed foreign freehold in designated areas since the early 2000s, and Qatar and Bahrain operate similar zoned regimes, so the reform brings the region’s largest economy into line with a model its neighbours have used for two decades to attract property capital. The design choices shape how it competes. A 2 percent disposal fee is a transaction cost paid on sale rather than an annual holding tax, which keeps the ongoing cost of ownership low, while the designated-zone structure concentrates foreign demand in the giga-projects and financial districts that the state is building, aligning private inflows with public investment priorities. For a housing market where mortgage penetration has been expanding under the Vision 2030 programme, adding international buyers widens the demand base at a time when the kingdom is delivering a large pipeline of new residential and mixed-use supply.
Why it matters: Opening real-estate ownership to non-Saudis is one of the more consequential structural reforms of the diversification agenda, because property is both a store of foreign capital and a signal of confidence in a market’s rules. A clear, moderate transaction fee, set well below the legal ceiling, and a designated-zone model that channels foreign money toward the flagship developments are designed to attract investment while keeping control over sensitive locations. For Saudi Arabia the measure supports the giga-project financing model and the goal of drawing sustained foreign direct investment, and for the wider Gulf, where the UAE, Qatar and others already allow foreign freehold in defined zones, it brings the region’s largest economy into closer alignment with a competitive regional norm for attracting international property capital.
Beyond attracting capital, the fee has a fiscal and formalisation dimension. A registered 2 percent charge on every non-Saudi disposal creates a transparent, recurring revenue stream and pulls more of the property market into the formal, taxed economy, which supports the broader goal of lifting non-oil revenue. How much it raises will depend on transaction volumes, but the principle of taxing turnover lightly rather than penalising ownership is consistent with keeping the market attractive to foreign buyers while still capturing value for the state.
Outlook: The test is execution and take-up. How quickly foreign buyers and developers engage will depend on the clarity of the zone rules, the ease of registration and financing, and confidence in the legal framework. Strong early interest would reinforce the giga-project investment case and broaden the buyer base for Saudi real estate, while the pace of transactions and any further guidance from the Real Estate General Authority will show how far the opening translates into actual inflows.
Sources: Saudi Real Estate General Authority; Saudi Press Agency.






