ECB Flags AI Debt and Fiscal Risks as Banks Post Their Best Returns in a Decade

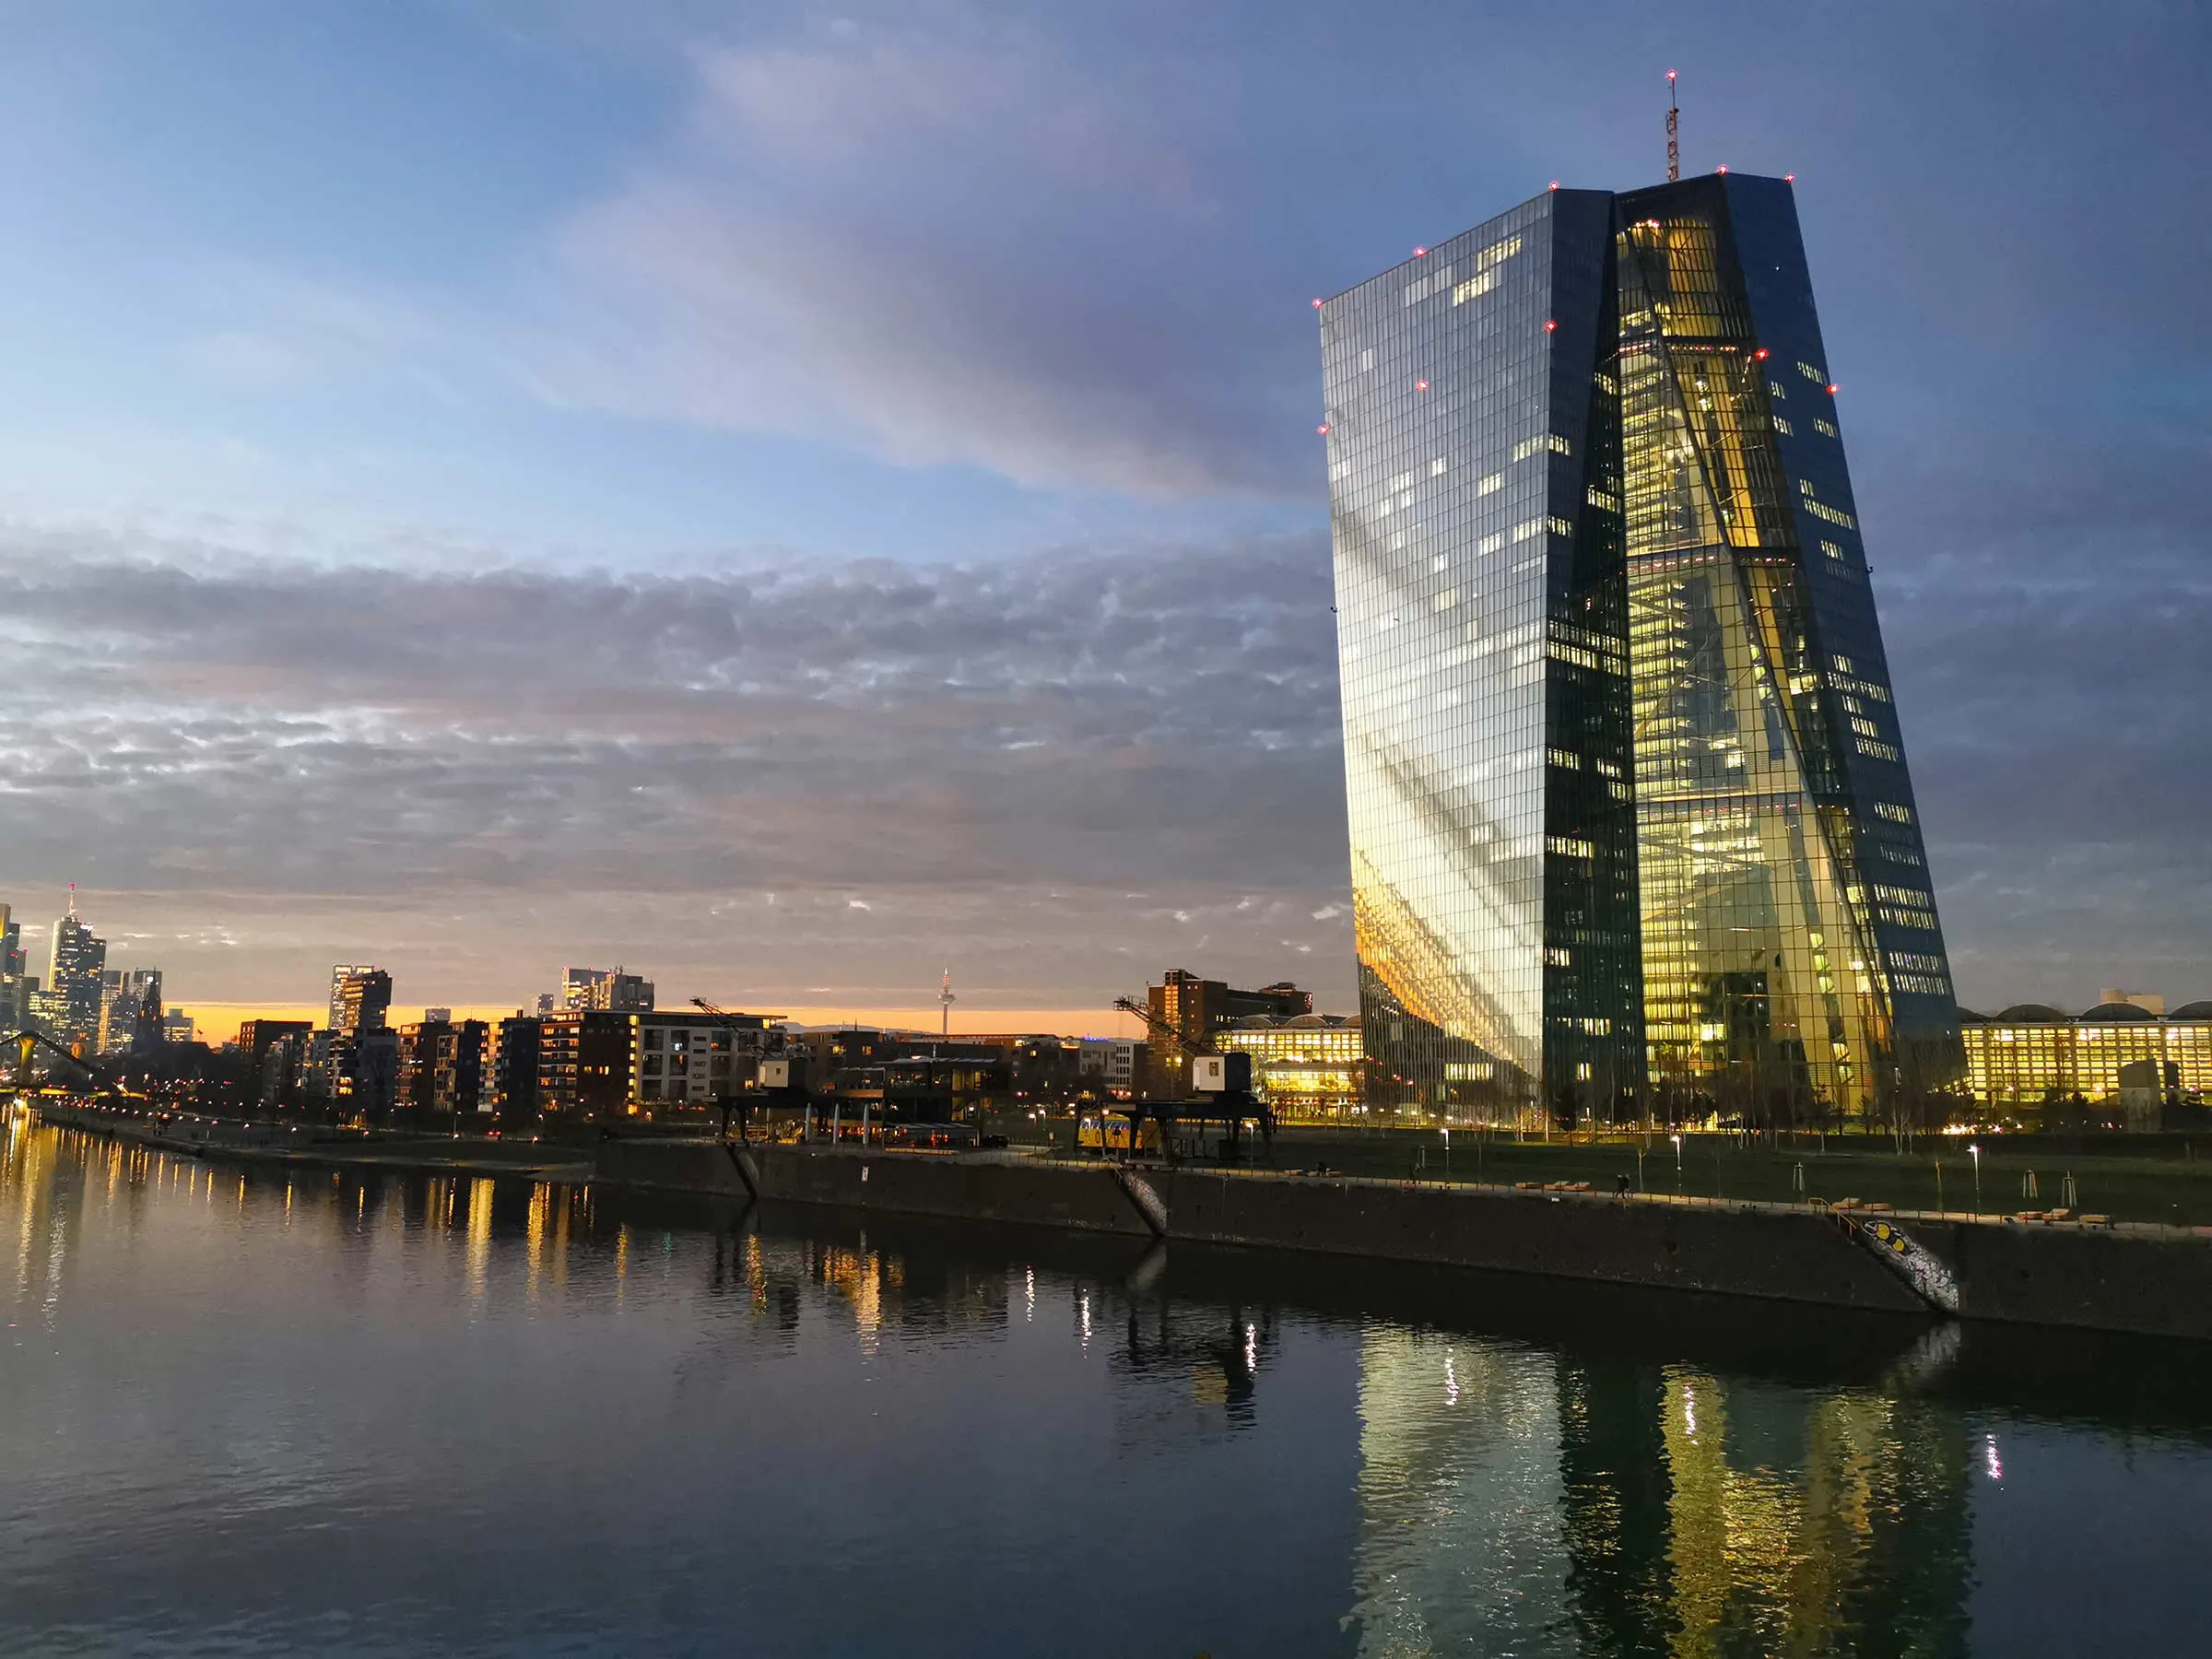
The Takeaway: The European Central Bank’s latest Financial Stability Review puts AI valuations at the top of its risk list, ahead of fiscal strains and the exposures of banks and non-banks. Euro area banks meet those risks with their best return on equity in a decade, while the weaker spots sit in parts of the non-bank sector. France’s long-term yield gap over Germany averaged 1.47 percentage points in October, up from 0.69 in May, and the bank figures run only to June, before most of that widening.
Euro area financial stability risks “remain elevated”, European Central Bank Vice-President Boris Vujčić said on 18 November, as its new review paired AI and fiscal warnings with decade-high bank returns.
The order of concerns has changed since the last edition. In May the first risk on the list was a market sell-off driven by geopolitical tension and worries over public finances, after war broke out in the Middle East in February. This edition opens with share prices that depend on very high earnings growth at AI firms.
The second risk is the path of public finances, which could test investor confidence in government debt. The third is how exposed banks are to these shocks, along with non-banks, the funds, insurers and pension schemes outside the banking system. The report warns that all three could materialize together and amplify one another.
AI spending now leans on borrowing
Capital spending by US big tech firms is projected to total about $5.5 trillion by 2030, on broker forecasts that the Review says vary widely.
Most hyperscalers, the largest cloud computing groups, saw free cash flow, the cash left after investment, turn negative in 2026. It is expected to stay negative until 2028.
Debt is filling the gap. Issuance for AI infrastructure has hit new records this year. Big tech firms are also estimated to carry more than $4 trillion of off-balance-sheet commitments, contracts to use data centers and advanced chips that work like debt but are not recorded as liabilities. That is well above the liabilities on their balance sheets. The cost of insuring some of these firms’ debt against default has climbed to record levels.
Overall AI investment needs are put at more than 3% of US GDP a year between 2025 and 2032, which the central bank calls considerably larger than the financing of past innovations. The internet boom took 1.10% of GDP a year and the nineteenth-century Northern Pacific Railway about 2.24%.
Share sales are rising as well: analysts project US listing proceeds for 2026 at more than five times the 2025 total, and issuance is on track to pass the dotcom peak as a share of US GDP.
The Review also sets out the other side. The technology may prove as transformative as investors expect, and there is only limited evidence so far that AI borrowing is crowding out other issuers in euro markets. Euro area shares, less tied to technology, have tended to lose less after tech shocks and recover faster than US shares.
AI financing in the Review
| Measure | Figure |
|---|---|
| US big tech capital spending to 2030 | Est. $5.5tn |
| Big tech off-balance-sheet commitments | Over $4tn |
| AI investment needs 2025 to 2032, share of US GDP a year | Over 3% |
| Internet boom 1996 to 2003, share of US GDP | 1.10% |
| Northern Pacific Railway 1870 to 1890, share of US GDP | Est. 2.24% |
| Hyperscaler dollar bonds, 2026 to date | Over $200bn |
| US listing proceeds, 2026 projection | Est. $225bn |
| US listing proceeds, 2025 | Est. $44bn |
| Euro area bank lending to AI firms, broad measure | Est. EUR 75bn |
Figures marked Est. are approximations as the Review gives them. Dollar bonds are investment-grade corporate issues, the higher-rated tier of the market.
France pays more as government borrowing climbs
Issuance by euro area governments has reached its highest level since the pandemic, driven mainly by Germany’s defense and infrastructure package. Many countries now face their highest financing costs since the 2012 sovereign debt crisis, and a quarter of outstanding euro area sovereign debt falls due before the end of 2028.
France stands out. The extra yield investors demand to hold its 10-year bonds over Germany’s averaged 1.47 percentage points in October, the widest monthly average since November 2011 on The Edge’s calculation from the central bank’s yield series. In May, when the last Review appeared, the gap was 0.69 points.
France’s yield has risen 1.15 points since May, against 0.37 points for Germany. Its October level was the highest monthly average since July 2002.
The central bank’s deposit rate, what banks earn on overnight deposits with it, rose 0.50 points over the same stretch, to 2.50%. German yields moved less than the policy rate, and French yields more than twice as much.
In October France yielded 0.21 points more than Italy, after yielding 0.10 points less in May.
The central bank links the widening to long-standing fiscal concerns and to political risk ahead of elections in 2027, with German bonds gaining from their relative safe-haven status. It adds that markets have kept functioning in an orderly way. The average spread for eight other euro area members, though wider, remains low against earlier periods of stress.
Ten-year government bond yields, monthly average (in %)
| Country | May 26 | Sep 26 | Oct 26 |
|---|---|---|---|
| Germany | 3.05 | 3.47 | 3.42 |
| France | 3.74 | 4.44 | 4.89 |
| Italy | 3.84 | 4.36 | 4.68 |
| Spain | 3.49 | 3.93 | 4.07 |
| France gap | 0.69 | 0.97 | 1.47 |
Harmonized long-term interest rates for convergence purposes. The France gap is France less Germany, in percentage points.
Banks start from strength, on data that end in June
Euro area banks enter this phase with their best returns in a decade. Measured over the latest four quarters, return on equity, the profit earned on shareholders’ capital, reached its highest level in ten years, and the cost-to-income ratio, the share of income absorbed by running costs, fell to its lowest since 2015.
The non-performing loan ratio, the share of loans no longer being repaid as agreed, stood at 2.2% in the second quarter, a record low. A wider measure that also counts cash balances was 1.89%, above its low of 1.79% in the third quarter of 2022.
The Common Equity Tier 1 ratio, the core capital banks hold against losses, stood at 16.00%, which is 0.28 points below the end of 2025. Capital, the report says, is stable at high levels and well above requirements.
Pressure is building at the edges. Loan loss provisions, money set aside for bad debts, rose 12% in the first half from a year earlier, although strong loan growth meant their ratio to total loans edged up only slightly from the end of 2025. Bad-loan ratios for small and medium-sized firms have been edging up in France and Germany since 2023, and consumer loan quality has kept worsening.
In energy-intensive sectors the bad-loan ratio was unchanged at 4.2%, but the report expects the oil supply shock to hurt asset quality in the coming quarters.
Direct exposure to AI is small. On a broad measure, AI-related lending by euro area banks comes to around EUR 75 billion, or 1.1% of their committed corporate exposures.
In The Edge’s reading, the strongest bank figures and the sharpest bond moves belong to different periods: the supervisory data end in June, when the French gap stood at 0.72 points, and the gap has more than doubled since. Bank share valuations have already given back part of their gains on sovereign worries in a few countries, the Review notes.
Euro area significant banks (in %)
| Measure | Q2 2025 | Q4 2025 | Q2 2026 |
|---|---|---|---|
| Return on equity | 10.11 | 9.53 | 10.73 |
| CET1 ratio | 16.09 | 16.28 | 16.00 |
| NPL ratio | 2.22 | 2.19 | 2.17 |
Significant institutions in the countries of European banking supervision, on a changing sample. The NPL (non-performing loan) ratio excludes cash balances. Return on equity here is the supervisory series, which reached its highest level since the series began in 2015; the Review’s decade-high measure is a four-quarter trailing figure.
Non-banks carry the sharper weak spots
The Vice-President said vulnerabilities are more pronounced in certain non-banks, where risks are growing and safeguards are less developed. US technology and AI-related firms now make up between 16% and 26% of these investors’ equity holdings.
An estimated half of the largest euro area high-yield bond funds, investors in lower-rated corporate debt, lack enough liquid assets to cover a redemption shock. US hedge funds have more than doubled their repo borrowing, short-term loans secured on bonds, since 2023. A US hedge fund’s near collapse in July is the report’s example of concentrated positions meeting leverage.
Non-banks have also remained key buyers of government debt, taking an estimated 20% of issuance under five years and more than 30% of longer maturities over the past 12 months. The report counts hedge funds, investment funds and foreign investors among the more procyclical buyers of this debt, those whose trading tends to amplify market swings, and warns that hedge funds may be forced to cut leverage under stress.
Links with banks run both ways. Bank lending to investment funds and hedge funds has risen markedly, while banks rely more on non-bank funding, so strain in one sector could travel quickly to the other. The central bank’s policy call is to keep banks’ releasable capital buffers, reserves that authorities can free up in a shock. Among non-banks it wants action on leverage and on liquidity mismatches, where investors can redeem faster than assets can be sold.
What to watch: The central bank’s Governing Council holds its next monetary policy meeting on 16 and 17 December, with a press conference on the second day, its first rate decision since this Review. The next Financial Stability Review is due on 26 May 2027.
Correction, 18 November 2026: An earlier version said non-banks had become key buyers of government debt over the past year. The European Central Bank’s Review says they have continued to be key buyers.
Method: based on the European Central Bank’s press release and Financial Stability Review of 18 November 2026 and its Review of 27 May 2026, with yields from its harmonized long-term interest rate statistics to October 2026 and bank ratios from its supervisory banking statistics to the second quarter of 2026. Yield gaps, changes and multiples not printed in those documents are The Edge’s calculations; the rankings of the French gap and the French yield compare monthly averages from January 1990 to October 2026.
Sources: European Central Bank, The Edge.